Economic Indicators, Stock Market & Investment Reports

Showing posts with label Banking. Show all posts

9.13.2012

Fed Announces Open-Ended Bond Purchases - QE3


The Federal Reserve on Thursday announced that it is launching a new program of open-ended bond purchases, so-called QE3, saying it will buy $40 billion of agency mortgage-backed securities each month as long as the economy needs it, starting Friday.

It's also keeping in place so-called Operation Twist, which consists of swapping short-dated securities for longer-term securities, as well as reinvesting the proceeds of maturing securities, so the central bank will be adding $85 billion of long-term securities each month through the end of the year.

The Fed is also extending its plan to keep interest rates exceptionally low until at least through mid-2015. Fed funds rates are currently targeted at a rate between 0% and 0.25%.

The Fed said it's acting "to support a stronger economic recovery" and expects the new program to put downward pressure on longer-term interest rates, support mortgage markets and help make financial conditions more accommodative.

U.S. stocks added to Thursday gains after the Federal Open Market Committee announced a new round of buying mortgage-backed securities.

7.05.2012

LIBOR Rigging

LIBOR (the London inter-bank offered rate) scandal that involves Barclays, a 300-year-old British bank, is beginning to assume global significance. Over the past weeks damning evidence has emerged, in documents detailing a settlement between Barclays and regulators in America and Britain that employees at the bank and at several other unnamed banks tried to rig the number time and again over a period of at least five years. And worse is likely to emerge. Investigations by regulators in several countries, including Canada, America, Japan, the EU, Switzerland and Britain, are looking into allegations that LIBOR and similar rates were rigged by large numbers of banks.

The LIBOR that the traders were toying with determines the prices that people and corporations around the world pay for loans or receive for their savings. It is used as a benchmark to set payments on about $800 trillion-worth of financial instruments, ranging from complex interest-rate derivatives to simple mortgages. The number determines the global flow of billions of dollars each year. Yet it turns out to have been flawed.

Bob Diamond resign over LIBOR riggingOn July 3rd, Barclays PLC Chief Executive Robert Diamond caved in to intense pressure to quit after the U.K. bank became embroiled in a bitter political row over its role in the Libor rate-rigging scandal. Robert Diamond resigned amid a deepening dispute about whether the Bank of England pushed the lender to submit artificially low Libor rates during the financial crisis.

Like many of the City’s ways, LIBOR is something of an anachronism, a throwback to a time when many bankers within the Square Mile knew one another and when trust was more important than contract. For LIBOR, a borrowing rate is set daily by a panel of banks for ten currencies and for 15 maturities. The most important of these, three-month dollar LIBOR, is supposed to indicate what a bank would pay to borrow dollars for three months from other banks at 11am on the day it is set. The dollar rate is fixed each day by taking estimates from a panel, currently comprising 18 banks, of what they think they would have to pay to borrow if they needed money. The top four and bottom four estimates are then discarded, and LIBOR is the average of those left. The submissions of all the participants are published, along with each day’s LIBOR fix.

In theory, LIBOR is supposed to be a pretty honest number because it is assumed, for a start, that banks play by the rules and give truthful estimates. The market is also sufficiently small that most banks are presumed to know what the others are doing. In reality, the system is rotten.

First, it is based on banks’ estimates, rather than the actual prices at which banks have lent to or borrowed from one another.

A second problem is that those involved in setting the rates have often had every incentive to lie, since their banks stood to profit or lose money depending on the level at which LIBOR was set each day. Worse still, transparency in the mechanism of setting rates may well have exacerbated the tendency to lie, rather than suppressed it. Banks that were weak would not have wanted to signal that fact widely in markets by submitting honest estimates of the high price they would have to pay to borrow, if they could borrow at all. Read full article “LIBOR Rigging” at smartinmoney.com

6.25.2012

Operation Twist Extension: Latest Round of Monetary Easing

The Federal Reserve on June 20th it announced its seventh installment of unconventional monetary policy since running out of orthodox ammunition in late 2008, when short-term interest rates fell, in effect, to zero. It would purchase $267 billion of long-term bonds by the end of the year, paid for from the proceeds of sales of short-term bonds already in its portfolio.

The move extends a program, called Operation Twist (because it "twists" the slope of the yield curve on bonds) . To lower long-term interest rates down in the hope of stimulating demand, the Fed announced Operation Twist program last autumn and due to expire this month, under which the Fed has swapped $400 billion of short-term bonds for long-term ones. Previous initiatives have included purchasing bonds with newly created money (“quantitative easing”, or QE), reinvesting the proceeds of maturing bonds, and verbally committing to keeping rates near zero for ever longer periods.

This latest round of monetary easing, like its predecessors,  was motivated by the economy’s failure to grow as quickly as the Fed had forecast. Members of the Federal Open Market Committee (FOMC), the Fed’s main policymaking body, now expect growth of between 1.9% and 2.4% this year, down sharply from their April forecast of growth between 2.4% and 2.9%.

6.21.2012

Moody’s Slashed Credit Ratings of Big Banks

Moody’s Investors Service on Thursday slashed the credit ratings of 15 large financial firms. Citigroup and Bank of America, two United States banks that were hit hard in the financial crisis, are now rated only two notches above junk. While Morgan Stanley avoided a worst-case scenario of a three-notch downgrade, its rating slipped by two levels.

The downgrades are a serious blow for the banking industry, which is already dealing with the European sovereign debt crisis, a weak American economy and new regulations.

Moody’s downgrades are part of a broad effort to make its analysis more rigorous. The financial crisis stained the reputation of credit rating agencies. Both companies attached high ratings to mortgage-backed bonds that later suffered big losses in the housing bust.

Before the announcement on Thursday, bank shares continued to fall. Goldman Sachs, Citigroup, Bank of America and Morgan Stanley were all down for the day.

5.14.2012

JPMorgan's $2 Billion Loss

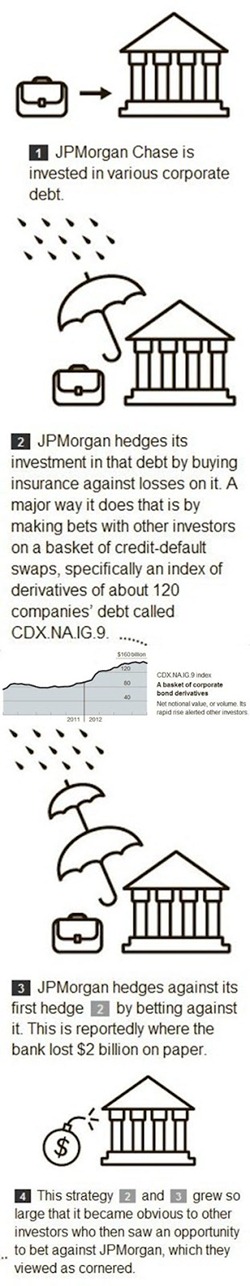
JPMorgan Chase CEO Jamie Dimon on Thursday revealed that the banking giant lost a $2 billion due to a massive trade that went sour, and that the losses could climb by another $1 billion in the coming days. Mr. Dimon said on Thursday that JPMorgan’s “synthetic credit portfolio,” an amalgam of derivatives and hedging bets that blew up in recent weeks, was part of “a strategy to hedge the firm’s overall credit exposure.”

Several days after announcing a $2 billion loss in its chief investment office, JPMorgan Chase is clearing house. Matthew E. Zames, the JPMorgan executive, was tapped Monday to replace the outgoing chief investment officer, Ina Drew.

The bank most likely structured the trade in a way that magnified losses (see the image). Read more “JPMorgan's Appalling $2 Billion Loss


JPMorgan Chase Complex Strategy

(The illustration is a courtesy off The New York Times)

5.12.2012

S&P & Fitch lowered J.P. Morgan rating due to $2B loss

J.P. Morgan Chase's Share Price

S&P cuts outlook on J.P. Morgan to negative

Standard & Poor's said late Friday it lowered its ratings outlook on J.P. Morgan Chase to negative from stable because of the bank's unexpected $2 billion loss on derivatives. S&P kept its A/A-1 issuer credit ratings on the bank and its A+/A-1 ratings on its subsidiaries.

S&P said it could lower its ratings by a notch if its determines that risk management mistakes were not limited to the specific credit portfolio mentioned late Thursday, or if it believes management is pursuing a more aggressive investment strategy than originally believed.

Fitch downgrades J.P. Morgan after trading loss

Fitch Ratings said on Friday it downgraded J.P. Morgan Chase & Co.'s long-term credit rating to A-plus from AA-minus, saying that while the $2 billion trading loss disclosed by the bank on Thursday is "manageable," the potential reputational risk and risk-governance issues raised are no longer consistent with an AA-minus rating. "The magnitude of the loss and ongoing nature of these positions implies a lack of liquidity," Fitch said in a statement after the stock market closed. "It also raises questions regarding J.P. Morgan's risk appetite, risk management framework, practices and oversight; all key credit factors."

Stock market reaction

Shares of J.P. Morgan closed down 9.3% on Friday and slipped further in after-hours trading.

U.S. stocks mostly slid Friday to a second weekly decline after a rise in consumer sentiment failed to outweigh J.P. Morgan Chase & Co.'s $2 billion trading loss, disclosed by the bank late Thursday.

The Dow Jones Industrial Average fell 34.44 points, or 0.3%, to 12,820.60, off 1.7% from the week-ago close. The S&P 500 retreated 4.6 points, or 0.3%, to 1,353.39, down 1.2% for the week. The Nasdaq Composite managed a fractional gain to close at 2,933.82, down 0.8% from last Friday's finish

3.14.2012

15 banks passed Fed’s stress tests


15 of 19 banks passed stress tests, but Citigroup, Suntrust Banks, Ally and Metlife failed!

The Federal Reserve said 15 of the 19 largest U.S. banks pass stress tests, or Comprehensive Capital and Analysis Review (CCAR), as they could maintain adequate capital levels even in a recession scenario in which they continue paying dividends and buy back stock. Four banks, including Citigroup, have more work to do and need more capital.

Under the stress scenario, unemployment rate of 13 percent, a 50 percent drop in stock prices and a 21 percent decline in prices would produce aggregate losses of $534 billion over nine quarters. Even with that blow, the 19 banks would see their tier one common capital ratio fall to 6.3 percent in the fourth quarter of 2013 in the hypothetical scenario, above the 5 percent minimum the Fed required. The ratio was 10.1 percent in the third quarter of last year.

It was the first time the Fed had released a thorough test of the banks' financial health since the early days of the financial crisis. The Fed has conducted the stress tests each year since 2009. The Fed did not publicize the results of its tests in 2010 or 2011. After the first round of tests, in 2009, the Fed ordered 10 banks to raise a total of $75 billion. Bank of America Corp. alone was told to raise $34 billion.